Swiss Finance Minister Warns Rising European Debt Could Trigger a Euro Crisis

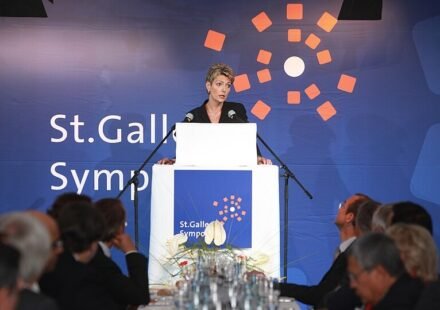
Switzerland’s Finance Minister Karin Keller-Sutter has warned that rising government debt in Europe and other major economies could threaten financial stability and potentially trigger a new euro crisis.
Speaking to Swiss broadcaster SRF in Bangkok on October 16, on the sidelines of the annual meetings of the International Monetary Fund (IMF) and the World Bank, Keller-Sutter highlighted concerns about the growing debt burden of major economies, particularly the United States and France.
She also pointed to rising energy prices as an additional challenge for policymakers already dealing with economic uncertainty.
Why Is Switzerland Concerned About European Debt?
Keller-Sutter said Switzerland’s relatively low public debt did not shield it completely from financial problems elsewhere in the world.
She explained that countries are closely connected through international financial markets, meaning a debt crisis in a major economy could affect others.
The Swiss finance minister specifically mentioned France, warning that its financial difficulties could contribute to a wider euro crisis if conditions deteriorated.
Her comments reflect concerns that governments with high borrowing requirements may face greater pressure if interest rates and debt-servicing costs remain elevated.
France’s Debt and Budget Deficit Under Scrutiny
France has become a focus of concern because of its high public debt, persistent budget deficits and relatively weak economic growth.
Political divisions have also complicated efforts to agree on measures to improve the country’s public finances. Uncertainty surrounding budget decisions can make investors more cautious about lending to governments, potentially increasing borrowing costs.
When governments spend a large share of their budgets servicing existing debt, they have less room to respond to economic slowdowns, rising public expenditure or unexpected emergencies.
However, financial pressure does not automatically mean that a sovereign debt crisis will occur. The outcome depends on factors including economic growth, government policies, investor confidence and the cost of refinancing debt.
Rising Energy Prices Add to Economic Concerns
Keller-Sutter also identified energy prices as a concern for policymakers. Higher energy costs can put pressure on households and businesses, contribute to inflation and complicate decisions about government spending.
If energy prices remain elevated, governments may face additional demands for financial support while also trying to control deficits and keep debt sustainable.
These competing pressures make it more difficult for policymakers to balance economic support with long-term fiscal discipline.
European Commission Says There Is No Current Sign of a Debt Crisis
The warning comes amid broader discussions about the sustainability of European public finances.
On October 14, European Economic Commissioner Valdis Dombrovskis told Reuters that there were no signs of a new euro zone sovereign debt crisis, although governments needed to maintain prudent fiscal policies as borrowing costs rose.
Dombrovskis said France’s proposed 2027 budget was important for providing clarity and stability regarding its financial outlook. He also noted that the relatively long average maturity of European government debt gives countries some time to respond before higher market yields feed fully into debt-servicing costs.
His comments provide an important distinction: policymakers are concerned about financial vulnerabilities, but that is not the same as saying a new crisis has already begun.
What Could a Euro Crisis Mean?
A serious sovereign debt crisis in the euro area could push up borrowing costs, weaken investor confidence and put pressure on banks and government budgets. It could also make financing more expensive for businesses and households.
The consequences would depend on which countries were affected, the scale of their financial difficulties and the response from European institutions and national governments.
For now, Keller-Sutter’s remarks serve as a warning about the risks posed by high public debt and the close links between international economies. Whether those risks develop into a wider crisis will depend on governments’ ability to manage borrowing, support sustainable growth and maintain confidence in public finances.
France Faces Weak Economic Momentum as Services Offset Industrial and Agricultural Slowdown
France’s economy is expected to grow by just 0.1% in the third quarter of 2026, highlighting the continuing weakness facing the euro zone’s second-largest economy, according to estimates from the Bank of France.
The central bank’s assessment points to modest overall growth as activity in services helps offset weakness in manufacturing, construction and agriculture. The estimate suggests that France’s recovery remains fragile after economic output stagnated in the second quarter.
The forecast is based on business surveys and other economic indicators. It is an estimate rather than the final official GDP figure for the July–September period.
Services Provide Support to the Economy
The services sector is expected to remain an important source of support for French economic activity. Information and communication, trade and business services are among the areas identified by the central bank as contributors to growth.
However, the improvement is not broad-based. Manufacturing has faced pressure from subdued production, while construction activity has been affected by weakness in public works and other building-related activity.
Agriculture has also faced challenges associated with extreme summer heat. The Bank of France estimated that the heatwave would weigh on third-quarter economic output, with agricultural activity particularly exposed to adverse weather conditions.
France’s Economic Recovery Remains Fragile
France recorded no GDP growth in the second quarter of 2026, according to revised national accounts published by the country’s statistics agency, INSEE.
The central bank’s latest estimate of 0.1% growth for the third quarter indicates only a limited improvement. Weak production and cautious business activity continue to constrain the pace of expansion.
The Bank of France’s September interim projections put full-year economic growth at 0.4% in 2026, below its previous forecast. The outlook reflects subdued activity during the first half of the year and uncertainty surrounding the domestic and international economic environment.
Household Spending and Business Investment Under Pressure
The economic outlook also faces challenges from consumer purchasing power and investment.
When prices rise faster than household incomes, consumers have less money available for discretionary spending. Businesses facing uncertain demand and higher financing costs may also delay investment decisions.
France’s fiscal position has added another source of uncertainty. The government is attempting to reduce its budget deficit, while political disagreements over public finances have attracted attention from financial markets.
The combination of weak growth, fiscal pressures and uncertainty could make it more difficult for policymakers to support activity without further straining public finances.
What the Forecast Means for the Euro Zone
France plays a significant role in the euro-zone economy, so persistent weakness could affect the region’s overall growth outlook.
However, the impact will depend on developments in other member states, consumer demand, industrial production and international trade. A single quarterly estimate does not establish the direction of the entire European economy.
Investors and policymakers will be watching the final GDP data, inflation figures and subsequent business surveys to determine whether the modest third-quarter expansion is sustained.
What Happens Next?
The 0.1% figure remains a central-bank estimate, and the final assessment will depend on official national accounts data.
For now, the forecast underlines the difficulty France faces in generating stronger economic growth. Services are providing some support, but weaknesses in industry, construction and agriculture continue to limit momentum.